WinningStrategy.ai Logo
WinningStrategy.ai
Home
AI Presentation AgentAI Spreadsheet AgentAI Dashboarding Agent
Investment BankingManagement ConsultingPrivate Equity
PricingBlogsAbout UsContact
Sign In
Home
PricingBlogsAbout UsContact
Sign InCreate Account

AI Analyst that delivers the work of a consulting team, in minutes

Every number auditable, so you can defend it with confidence

Try for FreeBook a Demo
Patient financing market size is estimated to be $615B
Market Sizing and Revenue Bridge (USD, 2026P)
Source: CMS National Health Expenditure Accounts 2024 baseline projected to 2026; CFPB medical debt research; KFF; company estimates.
Note: 2026P TAM projects patient-paid OOP spend only; SAM uses roughly 100M adults with medical debt; revenue assumes 8-12% take-rate on $7.2B annual financed volume.
Provider-led financing should focus on patient-paid exposure: ~260M users drive a $615B 2026P OOP TAM; 100M debt-burdened users create a $240B SAM, converting to $7.2B financed volume and $580M-$860M revenue.
TAM: $615B 2026P OOP
~260M users
SAM: $240B Medical Debt
100M users
SOM: $7.2B Annual Volume
Sizing LayerDefinition / Basis2026P FigureRevenue Bridge
TAMPatient-paid OOP spend
~260M users
$615BTotal addressable exposure
SAMMedical debt burden
100M adults
$240BPriority provider financing pool
SOMAnnual financed volume
initial penetration
$7.2BConvertible transaction volume
RevenuePlatform take-rate
8-12% of volume
$580M-$860MAnnual revenue opportunity
Bridge logic: $7.2B annual financed volume × 8-12% take-rate = $580M-$860M revenue pool.
TAM SAM SOM
US Patient Financing Market: TAM Segmentation
A US$240B serviceable addressable market emerges from financeable cash-pay categories within the US$615B patient responsibility pool, led by dental, elective outpatient, devices, and vision/hearing needs.
100%
75%
50%
25%
0%
US$150B
US$95B
US$110B
US$90B
US$50B
US$65B
Other hospital responsibility $60B
Inpatient balances $55B
Emergency care $35B
Other dental $15B
Implants & cosmetic $30B
Orthodontics $25B
Restorative dental $25B
Other outpatient & lab $40B
Specialist procedures $15B
Imaging & diagnostics $20B
Elective procedures $35B
Non-financeable prescriptions $50B
Specialty Rx bridge $18B
Devices & DME $22B
Optical retail $15B
Wellness $5B
Hearing aids $12B
Vision care $18B
Specialty therapy $20B
Behavioral health OOP $35B
Collections & charity $25B
Other financing gaps $40B
Hospital & emergency care
Dental & orthodontics
Outpatient procedures
Pharmacy & devices
Vision, hearing & wellness
Behavioral & specialty care
Other patient responsibility
Muted teal: outside immediate SAM
SAM focus = US$240B: dental US$95B + outpatient US$70B + pharmacy/devices US$40B + vision/hearing/wellness US$35B
Vibrant teal: SAM segments
Source: Illustrative market sizing based on US patient responsibility categories; company analysis, 2026E.
Note: TAM and SAM figures are directional estimates; SAM includes categories with higher consumer-financing fit and recurring / elective cash-pay behavior.
US$55B
TAM Segmentation
US Smartphone Price Ranges by Brand
Retailers should anchor premium inventory around Apple, Samsung, Sony, and Asus while using Motorola, TCL, and HMD for entry-tier coverage; the price ladder shows clear mid-tier whitespace from $300-$700.
Retail smartphone price ranges by brand in the USA, unlocked MRP / major retail prices, USD per handset
Brand
Retail price range, USD
Min
Avg
Max
$0
$500
$1,000
$1,500
$2,000
Sony
$899
$1,199
$1,399
Apple
$429
$999
$1,599
Asus
$699
$999
$1,299
Samsung
$160
$799
$1,919
Google
$349
$699
$999
OnePlus
$299
$599
$799
Nothing
$349
$499
$699
Motorola
$130
$350
$1,000
TCL
$100
$220
$500
HMD / Nokia
$90
$200
$400
Min-to-max range
Average price
Key Insights


Premium ceiling: Samsung and Apple carry the widest price ranges, with max models above $1,500 and $1,900 respectively.
Average ladder: Sony, Apple, and Asus cluster near $1,000 average MSRP, while TCL and HMD / Nokia anchor sub-$250 entry tiers.
Portfolio breadth: Motorola and Samsung span both entry and premium tiers, enabling carrier-promo flexibility across price bands.
Merchandising action: Protect $300-$700 shelf space for Google, OnePlus, Nothing, and Motorola to capture mid-tier Android switchers.
Source: Apple, Samsung, Google Store, Best Buy, Amazon US, carrier retail listings; analyst estimates, Jan 2025
Note: Prices are approximate unlocked MRP / major US retail ranges for active models; excludes refurbished devices, trade-in credits, and limited-time promotions.
Price Range
GenAI Decision Matrix
Manufacturers should pilot Edge AI for line-speed use cases, scale Plant Private Cloud for MES/SCADA-heavy analytics, and reserve sovereign or custom OT models for regulated IP, safety-critical control, and data residency constraints.
Manufacturing Tier
Architecture / OT Integration
Complexity
ROI / Payback
Est. Cost / Plant / Yr
Latency / OT Fit
Safety & IP Control
Shop-Floor
Edge AI
Plant Private
Cloud
Enterprise
Hybrid Cloud
Sovereign
Industrial
Cloud
Custom OT
Foundation
Line-side inference appliance
PLC / vision sensor integration
Local safety interlocks
◑
0-3 Months
Safety-critical
$150k - $600k
On-prem GPU appliance
MES / SCADA connectors
Batch + quality analytics
◕
3-9 Months
Plant default
$0.8m - $3.5m
Central model governance
Federated plant deployment
ERP / PLM integration
◕
6-12 Months
Scale leverage
$2.0m - $8.0m
Regional data residency
Vendor-managed secure stack
Validated safety controls
◕
12+ Months
Compliance-led
$5.0m - $18.0m
Proprietary model training
Full IP and recipe control
Capital-intensive MLOps
●
Long-term
Strategic IP
$40m+ upfront
▲
▲
▲
▲
▲
Decision Framework: Anchor on latency and safety risk: deploy edge AI for line-speed inspection and control, use plant private cloud for MES/SCADA-heavy analytics, scale enterprise hybrid only after governance, and reserve sovereign/custom OT foundation for regulated IP and recipes.
Source: Company analysis; manufacturing AI/ML architecture benchmarks; industrial cloud and edge inference pricing, 2025
Legend: OT Complexity ○ low ◑ medium ◕ high ● very high; Latency / OT Fit bar: red = poor, yellow = moderate, green = strong; Safety & IP dots: red = low, amber = moderate, yellow = improving, lime = high, green = highest, pale = n/a.
Decision Matrix
Transaction Considerations: Adjusted EBITDA
Normalize reported results before valuation reliance; the largest EBITDA adjustments relate to owner compensation, transaction costs, provisions and revenue cut-off timing.
Adjusted EBITDA
USD $0002020A2021A2022AYTD 2022YTD 2023
Reported EBITDA1,5632,1952,6471,7792,071
Non-recurring income(42)(128)(91)(66)(44)
Owner / management salaries315342365274281
Professional fees851121248396
Rent and facilities normalisation6472795961
Transaction and diligence costs-461187285
Inventory and warranty provisions91761098274
Other one-off adjustments3854613745
Total EBITDA adjustments551574765541598
Adjusted EBITDA2,1142,7693,4122,3202,669
Adjusted EBITDA margin13.2%14.5%15.1%14.7%15.6%
YoY growthn/a31.0%23.2%n/a15.0%
Adjusted Revenue
USD $0002020A2021A2022AYTD 2023
Reported revenue15,98719,10522,64117,088
Revenue cut-off adjustment(120)8514095
Customer rebates / credits(64)(91)(118)(76)
Out-of-period sales42(35)(58)(21)
Total revenue adjustments(142)(41)(36)(2)
Adjusted revenue15,84519,06422,60517,086
Commentary and adjustment basis
Commentary: Management's adjusted EBITDA reconciles reported results to a normalized run-rate view by removing non-recurring items, owner compensation differences and transaction-related costs.

Primary adjustment areas: Owner compensation, transaction costs, inventory and warranty provisions, and revenue cut-off timing around period-end shipments.
Takeaway: Adjusted EBITDA expands from $2.1m in 2020A to $3.4m in 2022A and $2.7m YTD 2023; validate salary normalization, transaction costs and provision methodology before relying on the run-rate margin.
Source: Management accounts and company-provided adjustment schedules.
Note: Figures shown in USD thousands; adviser branding from the source image has been omitted.
Adjusted EBITDAFinance
Primary Technology
EV/MW Trading Multiples
EV/MW Transaction Multiples
Commentary
EV change in %
MW change in %
Wind Parks Command Higher EV/MW Multiples
1.720231.620241.52025
1.520231.520241.62025
1.120231.220241.22025
1.220231.320241.32025
Higher full-load hours support premium wind EV/MW pricing; from 2023 to 2025, projected capacity growth continues to outpace EV growth across renewable energy companies, keeping trading multiples compressed while transaction pricing stabilizes.
Wind commentary
• Trading multiples are projected to ease from 1.7x to 1.5x.
• MW additions continue to grow faster than enterprise value.
• Transaction multiples stay resilient at 1.5x to 1.6x, signaling premium buyer pricing.
Solar commentary
• Trading multiples stabilize around 1.1x to 1.2x.
• Transaction multiples normalize from 1.2x to 1.3x.
• 2025 remains below wind, reflecting lower full-load-hour economics.
EV/MW interpretation

• EV/MW measures enterprise value per MW of installed capacity.
• Wind generally earns higher EV/MW because full-load hours are stronger.
• From 2023 to 2025, MW growth is projected to outpace EV growth for both wind and solar.
• Result: capacity additions keep trading multiples compressed, while transaction pricing shows early stabilization.
Projected changes in EV and MW among renewable energy companies (2023 - 2025)
+8%
+22%
+12%
+18%
Source: Public renewable energy company filings; S&P Capital IQ; company analysis projections
Note: Multiples shown as EV/MW; periods shown for 2023-2025. 2024-2025 values are illustrative projections based on current market trends.
Valuation MultiplesFinance
Manufacturing Profitability Roadmap
Manufacturing margin expansion starts from a 2026 baseline: execute automation, supply-chain optimization, and predictive maintenance to lift EBITDA margin from 8.5% to 13.7% by 2028.
EBITDA Margin Expansion Waterfall (% of Sales)
8.52026 Base1.2Price/Mix0.8Yield/Scra1.5Automation1Supply Cha0.7Maint.13.72028 Targe
2026 baseline
Margin levers
2028 target
2026 Baseline
8.5% EBITDA margin
92% OEE on bottleneck lines
5.8% scrap and rework
Phase 1
11.0% EBITDA margin
Automation in top 3 value streams
2.0 pts cost take-out
Phase 2 Target
13.7% EBITDA margin
Predictive maintenance scaled
40 bps warranty reduction
Profitability Lever Roadmap
Margin lift
Cost take-out
Smart Automation
Supply Chain Optimization
Predictive Maintenance
Pricing / Mix Discipline
Energy & Scrap Reduction
Strategic Priorities: Margin Expansion
Smart Automation
Automate high-variance, labor-intensive stations to raise throughput, stabilize quality, and unlock 1.5 pts of EBITDA margin.
Supply Chain Optimization
Re-source strategic inputs, redesign safety stocks, and renegotiate freight lanes to reduce material and logistics cost volatility.
Predictive Maintenance
Instrument critical assets, predict failures, and shift maintenance from reactive repair to uptime assurance across bottleneck lines.
Source: Company manufacturing operations analysis; 2026 baseline and 2028 margin-expansion roadmap.
Note: Margin values are illustrative EBITDA margin percentages; waterfall drivers represent estimated percentage-point contribution to profitability improvement.
Profitability RoadmapFinance
5562707896881208691827486768478897268626675202120222023202420252026
Russia-Ukraine conflict begins
Demand decline (China lockdowns, unusually warm European winter, USD appreciation)
Weather then expected demand from China reopening
Voluntary OPEC+ output cuts, held as inventory drawdowns
Start of Israel-Hamas War
Red Sea attacks
202120222023202420252026
Supply > Demand = Inventory Build
Demand > Supply = Inventory Draw
Note: Monthly average of Brent crude oil price (USD per barrel)
Crude Oil Prices and Inventories
Brent crude oil spot prices and global inventory changes
Drivers of energy prices in 2026
Supply disruptions lifted Brent prices in early 2026, but rising OPEC+ output and softer demand point to inventory builds and renewed price pressure through 2026
Near-term price spike: Brent rose by around $10/barrel since end-2025 as North American winter outages and Kazakhstan field power disruptions constrained supply.

Supply surplus re-emerging: Higher OPEC+ output and the unwinding of earlier voluntary cuts should shift balances back toward inventory builds in coming months.

Demand remains soft: Weak industrial activity, particularly in China, limits absorption of incremental supply and reinforces downside pressure on prices.

Geopolitics add volatility: US-Iran tensions can trigger short-lived price spikes, but have not changed the broader supply-surplus outlook.
Sources: International Energy Agency, Reuters, U.S. Energy Information Administration, World Bank, Bloomberg, Haver Analytics
MacroeconomicsFinance
Commercial Due Diligence: Strategic Initiatives Impact
Implementing private label expansion, digital ordering, and supply chain finance drives 280 bps EBITDA margin expansion and unlocks $150M in working capital.
FY28 REVENUE TARGET
$1.25B
8.3% CAGR FY24-FY28
EBITDA MARGIN
5.8%
+280 bps vs baseline
CASH CONVERSION CYCLE
16 Days
8 day improvement
WORKING CAPITAL UNLOCKED
$150M
Through inventory optimization + SCF
5-Year P&L Trajectory ($M)
MetricFY24 (Base)FY25FY26FY27FY28 Target
Net Sales ($M)$910$986$1,068$1,157$1,250
Gross Margin15.5%16.2%16.8%17.3%17.8%
Operating Expenses12.5%12.3%12.2%12.0%12.0%
EBITDA ($M)$27.3$38.5$49.1$61.3$72.5
EBITDA Margin3.0%3.9%4.6%5.3%5.8%
EBITDA Margin Bridge: FY24 to FY28
EBITDA Margin (%)02463.0FY24 Base+1.2Digital Ops+0.3SCF Impact+1.3Private Label5.8FY28+280 bps total
Strategic Implication: By implementing Supply Chain Finance to unlock $150M in working capital in Year 1, the company can self-fund high-ROI automation investments and private label expansion. This execution shifts the financial profile from an industry-average 3.0% EBITDA to best-in-class 5.8%, driving a 2.7x increase in absolute EBITDA by FY28.
Source: FY2024 management accounts; Commercial due diligence interviews; company operating data
Note: Projections are illustrative; EBITDA bridge reflects estimated impact of identified strategic initiatives.
Commercial Due Diligence
Patient financing market size is estimated to be $615B
Market Sizing and Revenue Bridge (USD, 2026P)
Source: CMS National Health Expenditure Accounts 2024 baseline projected to 2026; CFPB medical debt research; KFF; company estimates.
Note: 2026P TAM projects patient-paid OOP spend only; SAM uses roughly 100M adults with medical debt; revenue assumes 8-12% take-rate on $7.2B annual financed volume.
Provider-led financing should focus on patient-paid exposure: ~260M users drive a $615B 2026P OOP TAM; 100M debt-burdened users create a $240B SAM, converting to $7.2B financed volume and $580M-$860M revenue.
TAM: $615B 2026P OOP
~260M users
SAM: $240B Medical Debt
100M users
SOM: $7.2B Annual Volume
Sizing LayerDefinition / Basis2026P FigureRevenue Bridge
TAMPatient-paid OOP spend
~260M users
$615BTotal addressable exposure
SAMMedical debt burden
100M adults
$240BPriority provider financing pool
SOMAnnual financed volume
initial penetration
$7.2BConvertible transaction volume
RevenuePlatform take-rate
8-12% of volume
$580M-$860MAnnual revenue opportunity
Bridge logic: $7.2B annual financed volume × 8-12% take-rate = $580M-$860M revenue pool.
TAM SAM SOM
US Patient Financing Market: TAM Segmentation
A US$240B serviceable addressable market emerges from financeable cash-pay categories within the US$615B patient responsibility pool, led by dental, elective outpatient, devices, and vision/hearing needs.
100%
75%
50%
25%
0%
US$150B
US$95B
US$110B
US$90B
US$50B
US$65B
Other hospital responsibility $60B
Inpatient balances $55B
Emergency care $35B
Other dental $15B
Implants & cosmetic $30B
Orthodontics $25B
Restorative dental $25B
Other outpatient & lab $40B
Specialist procedures $15B
Imaging & diagnostics $20B
Elective procedures $35B
Non-financeable prescriptions $50B
Specialty Rx bridge $18B
Devices & DME $22B
Optical retail $15B
Wellness $5B
Hearing aids $12B
Vision care $18B
Specialty therapy $20B
Behavioral health OOP $35B
Collections & charity $25B
Other financing gaps $40B
Hospital & emergency care
Dental & orthodontics
Outpatient procedures
Pharmacy & devices
Vision, hearing & wellness
Behavioral & specialty care
Other patient responsibility
Muted teal: outside immediate SAM
SAM focus = US$240B: dental US$95B + outpatient US$70B + pharmacy/devices US$40B + vision/hearing/wellness US$35B
Vibrant teal: SAM segments
Source: Illustrative market sizing based on US patient responsibility categories; company analysis, 2026E.
Note: TAM and SAM figures are directional estimates; SAM includes categories with higher consumer-financing fit and recurring / elective cash-pay behavior.
US$55B
TAM Segmentation
US Smartphone Price Ranges by Brand
Retailers should anchor premium inventory around Apple, Samsung, Sony, and Asus while using Motorola, TCL, and HMD for entry-tier coverage; the price ladder shows clear mid-tier whitespace from $300-$700.
Retail smartphone price ranges by brand in the USA, unlocked MRP / major retail prices, USD per handset
Brand
Retail price range, USD
Min
Avg
Max
$0
$500
$1,000
$1,500
$2,000
Sony
$899
$1,199
$1,399
Apple
$429
$999
$1,599
Asus
$699
$999
$1,299
Samsung
$160
$799
$1,919
Google
$349
$699
$999
OnePlus
$299
$599
$799
Nothing
$349
$499
$699
Motorola
$130
$350
$1,000
TCL
$100
$220
$500
HMD / Nokia
$90
$200
$400
Min-to-max range
Average price
Key Insights


Premium ceiling: Samsung and Apple carry the widest price ranges, with max models above $1,500 and $1,900 respectively.
Average ladder: Sony, Apple, and Asus cluster near $1,000 average MSRP, while TCL and HMD / Nokia anchor sub-$250 entry tiers.
Portfolio breadth: Motorola and Samsung span both entry and premium tiers, enabling carrier-promo flexibility across price bands.
Merchandising action: Protect $300-$700 shelf space for Google, OnePlus, Nothing, and Motorola to capture mid-tier Android switchers.
Source: Apple, Samsung, Google Store, Best Buy, Amazon US, carrier retail listings; analyst estimates, Jan 2025
Note: Prices are approximate unlocked MRP / major US retail ranges for active models; excludes refurbished devices, trade-in credits, and limited-time promotions.
Price Range
GenAI Decision Matrix
Manufacturers should pilot Edge AI for line-speed use cases, scale Plant Private Cloud for MES/SCADA-heavy analytics, and reserve sovereign or custom OT models for regulated IP, safety-critical control, and data residency constraints.
Manufacturing Tier
Architecture / OT Integration
Complexity
ROI / Payback
Est. Cost / Plant / Yr
Latency / OT Fit
Safety & IP Control
Shop-Floor
Edge AI
Plant Private
Cloud
Enterprise
Hybrid Cloud
Sovereign
Industrial
Cloud
Custom OT
Foundation
Line-side inference appliance
PLC / vision sensor integration
Local safety interlocks
◑
0-3 Months
Safety-critical
$150k - $600k
On-prem GPU appliance
MES / SCADA connectors
Batch + quality analytics
◕
3-9 Months
Plant default
$0.8m - $3.5m
Central model governance
Federated plant deployment
ERP / PLM integration
◕
6-12 Months
Scale leverage
$2.0m - $8.0m
Regional data residency
Vendor-managed secure stack
Validated safety controls
◕
12+ Months
Compliance-led
$5.0m - $18.0m
Proprietary model training
Full IP and recipe control
Capital-intensive MLOps
●
Long-term
Strategic IP
$40m+ upfront
▲
▲
▲
▲
▲
Decision Framework: Anchor on latency and safety risk: deploy edge AI for line-speed inspection and control, use plant private cloud for MES/SCADA-heavy analytics, scale enterprise hybrid only after governance, and reserve sovereign/custom OT foundation for regulated IP and recipes.
Source: Company analysis; manufacturing AI/ML architecture benchmarks; industrial cloud and edge inference pricing, 2025
Legend: OT Complexity ○ low ◑ medium ◕ high ● very high; Latency / OT Fit bar: red = poor, yellow = moderate, green = strong; Safety & IP dots: red = low, amber = moderate, yellow = improving, lime = high, green = highest, pale = n/a.
Decision Matrix
Transaction Considerations: Adjusted EBITDA
Normalize reported results before valuation reliance; the largest EBITDA adjustments relate to owner compensation, transaction costs, provisions and revenue cut-off timing.
Adjusted EBITDA
USD $0002020A2021A2022AYTD 2022YTD 2023
Reported EBITDA1,5632,1952,6471,7792,071
Non-recurring income(42)(128)(91)(66)(44)
Owner / management salaries315342365274281
Professional fees851121248396
Rent and facilities normalisation6472795961
Transaction and diligence costs-461187285
Inventory and warranty provisions91761098274
Other one-off adjustments3854613745
Total EBITDA adjustments551574765541598
Adjusted EBITDA2,1142,7693,4122,3202,669
Adjusted EBITDA margin13.2%14.5%15.1%14.7%15.6%
YoY growthn/a31.0%23.2%n/a15.0%
Adjusted Revenue
USD $0002020A2021A2022AYTD 2023
Reported revenue15,98719,10522,64117,088
Revenue cut-off adjustment(120)8514095
Customer rebates / credits(64)(91)(118)(76)
Out-of-period sales42(35)(58)(21)
Total revenue adjustments(142)(41)(36)(2)
Adjusted revenue15,84519,06422,60517,086
Commentary and adjustment basis
Commentary: Management's adjusted EBITDA reconciles reported results to a normalized run-rate view by removing non-recurring items, owner compensation differences and transaction-related costs.

Primary adjustment areas: Owner compensation, transaction costs, inventory and warranty provisions, and revenue cut-off timing around period-end shipments.
Takeaway: Adjusted EBITDA expands from $2.1m in 2020A to $3.4m in 2022A and $2.7m YTD 2023; validate salary normalization, transaction costs and provision methodology before relying on the run-rate margin.
Source: Management accounts and company-provided adjustment schedules.
Note: Figures shown in USD thousands; adviser branding from the source image has been omitted.
Adjusted EBITDAFinance
Primary Technology
EV/MW Trading Multiples
EV/MW Transaction Multiples
Commentary
EV change in %
MW change in %
Wind Parks Command Higher EV/MW Multiples
1.720231.620241.52025
1.520231.520241.62025
1.120231.220241.22025
1.220231.320241.32025
Higher full-load hours support premium wind EV/MW pricing; from 2023 to 2025, projected capacity growth continues to outpace EV growth across renewable energy companies, keeping trading multiples compressed while transaction pricing stabilizes.
Wind commentary
• Trading multiples are projected to ease from 1.7x to 1.5x.
• MW additions continue to grow faster than enterprise value.
• Transaction multiples stay resilient at 1.5x to 1.6x, signaling premium buyer pricing.
Solar commentary
• Trading multiples stabilize around 1.1x to 1.2x.
• Transaction multiples normalize from 1.2x to 1.3x.
• 2025 remains below wind, reflecting lower full-load-hour economics.
EV/MW interpretation

• EV/MW measures enterprise value per MW of installed capacity.
• Wind generally earns higher EV/MW because full-load hours are stronger.
• From 2023 to 2025, MW growth is projected to outpace EV growth for both wind and solar.
• Result: capacity additions keep trading multiples compressed, while transaction pricing shows early stabilization.
Projected changes in EV and MW among renewable energy companies (2023 - 2025)
+8%
+22%
+12%
+18%
Source: Public renewable energy company filings; S&P Capital IQ; company analysis projections
Note: Multiples shown as EV/MW; periods shown for 2023-2025. 2024-2025 values are illustrative projections based on current market trends.
Valuation MultiplesFinance
Manufacturing Profitability Roadmap
Manufacturing margin expansion starts from a 2026 baseline: execute automation, supply-chain optimization, and predictive maintenance to lift EBITDA margin from 8.5% to 13.7% by 2028.
EBITDA Margin Expansion Waterfall (% of Sales)
8.52026 Base1.2Price/Mix0.8Yield/Scra1.5Automation1Supply Cha0.7Maint.13.72028 Targe
2026 baseline
Margin levers
2028 target
2026 Baseline
8.5% EBITDA margin
92% OEE on bottleneck lines
5.8% scrap and rework
Phase 1
11.0% EBITDA margin
Automation in top 3 value streams
2.0 pts cost take-out
Phase 2 Target
13.7% EBITDA margin
Predictive maintenance scaled
40 bps warranty reduction
Profitability Lever Roadmap
Margin lift
Cost take-out
Smart Automation
Supply Chain Optimization
Predictive Maintenance
Pricing / Mix Discipline
Energy & Scrap Reduction
Strategic Priorities: Margin Expansion
Smart Automation
Automate high-variance, labor-intensive stations to raise throughput, stabilize quality, and unlock 1.5 pts of EBITDA margin.
Supply Chain Optimization
Re-source strategic inputs, redesign safety stocks, and renegotiate freight lanes to reduce material and logistics cost volatility.
Predictive Maintenance
Instrument critical assets, predict failures, and shift maintenance from reactive repair to uptime assurance across bottleneck lines.
Source: Company manufacturing operations analysis; 2026 baseline and 2028 margin-expansion roadmap.
Note: Margin values are illustrative EBITDA margin percentages; waterfall drivers represent estimated percentage-point contribution to profitability improvement.
Profitability RoadmapFinance
5562707896881208691827486768478897268626675202120222023202420252026
Russia-Ukraine conflict begins
Demand decline (China lockdowns, unusually warm European winter, USD appreciation)
Weather then expected demand from China reopening
Voluntary OPEC+ output cuts, held as inventory drawdowns
Start of Israel-Hamas War
Red Sea attacks
202120222023202420252026
Supply > Demand = Inventory Build
Demand > Supply = Inventory Draw
Note: Monthly average of Brent crude oil price (USD per barrel)
Crude Oil Prices and Inventories
Brent crude oil spot prices and global inventory changes
Drivers of energy prices in 2026
Supply disruptions lifted Brent prices in early 2026, but rising OPEC+ output and softer demand point to inventory builds and renewed price pressure through 2026
Near-term price spike: Brent rose by around $10/barrel since end-2025 as North American winter outages and Kazakhstan field power disruptions constrained supply.

Supply surplus re-emerging: Higher OPEC+ output and the unwinding of earlier voluntary cuts should shift balances back toward inventory builds in coming months.

Demand remains soft: Weak industrial activity, particularly in China, limits absorption of incremental supply and reinforces downside pressure on prices.

Geopolitics add volatility: US-Iran tensions can trigger short-lived price spikes, but have not changed the broader supply-surplus outlook.
Sources: International Energy Agency, Reuters, U.S. Energy Information Administration, World Bank, Bloomberg, Haver Analytics
MacroeconomicsFinance
Commercial Due Diligence: Strategic Initiatives Impact
Implementing private label expansion, digital ordering, and supply chain finance drives 280 bps EBITDA margin expansion and unlocks $150M in working capital.
FY28 REVENUE TARGET
$1.25B
8.3% CAGR FY24-FY28
EBITDA MARGIN
5.8%
+280 bps vs baseline
CASH CONVERSION CYCLE
16 Days
8 day improvement
WORKING CAPITAL UNLOCKED
$150M
Through inventory optimization + SCF
5-Year P&L Trajectory ($M)
MetricFY24 (Base)FY25FY26FY27FY28 Target
Net Sales ($M)$910$986$1,068$1,157$1,250
Gross Margin15.5%16.2%16.8%17.3%17.8%
Operating Expenses12.5%12.3%12.2%12.0%12.0%
EBITDA ($M)$27.3$38.5$49.1$61.3$72.5
EBITDA Margin3.0%3.9%4.6%5.3%5.8%
EBITDA Margin Bridge: FY24 to FY28
EBITDA Margin (%)02463.0FY24 Base+1.2Digital Ops+0.3SCF Impact+1.3Private Label5.8FY28+280 bps total
Strategic Implication: By implementing Supply Chain Finance to unlock $150M in working capital in Year 1, the company can self-fund high-ROI automation investments and private label expansion. This execution shifts the financial profile from an industry-average 3.0% EBITDA to best-in-class 5.8%, driving a 2.7x increase in absolute EBITDA by FY28.
Source: FY2024 management accounts; Commercial due diligence interviews; company operating data
Note: Projections are illustrative; EBITDA bridge reflects estimated impact of identified strategic initiatives.
Commercial Due Diligence
Our Accelerators

AI analyst that works for you
with outputs that you can trust

Market Research Agent

Get market research with citations for every number

AI Presentation Agent

Editable, consulting-grade presentations with auditable numbers
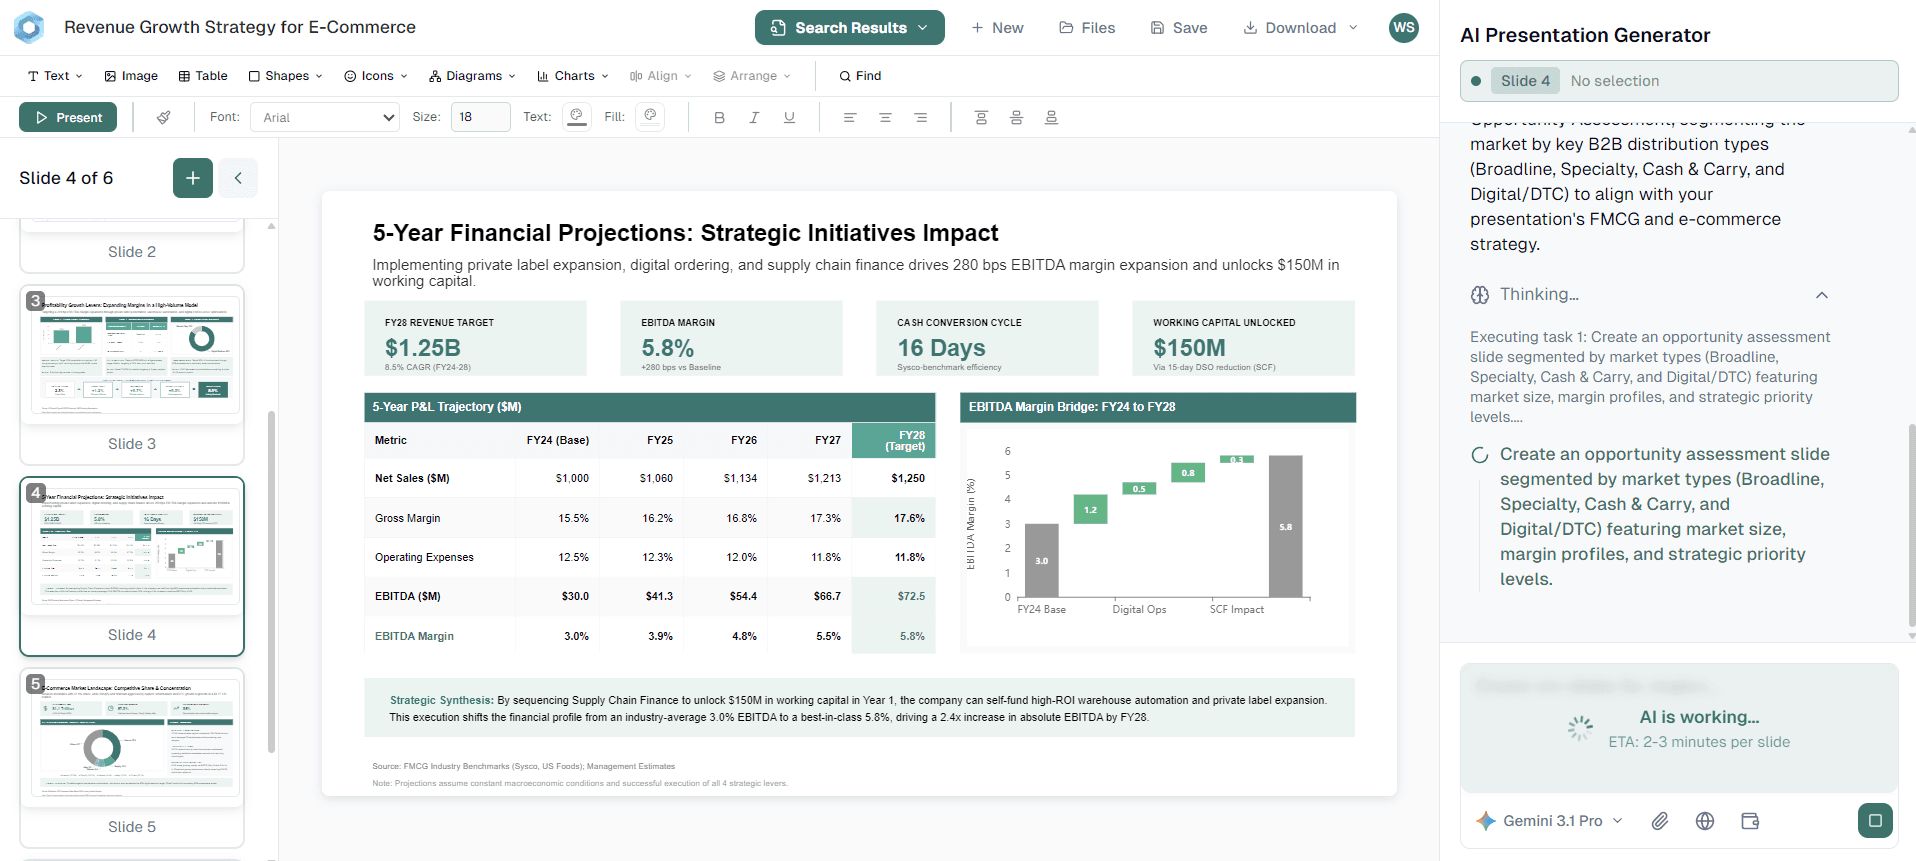
AI Presentation Agent | AI-powered business automation tool

AI Spreadsheet Agent

Iteratively corrects the assumptions for institutional-grade models

AI Dashboarding Agent

Create dashboards with high analytical depth from your data sources

Why Teams Choose Winning Strategy AI

AI Analyst with domain expertise
built in.

We understand how finance and consulting work: the workflows, terminology, and analytical frameworks.

Every number is auditable

Every number is auditable to its source. The exact quote is cited along with a clickable source link. In case of derived numbers, calculations are shown

Reasons using consulting frameworks for real analytical depth

Analysis is structured the way consultants work: MECE issue trees, driver decomposition, and benchmarking, making every output defensible

Implementation support by ex-consultants with deep domain knowledge

Built by ex-consultants who map how your team actually works, then tailor every output to your templates, colours, typography, and data sources.

Can be deployed locally for maximum data privacy and security

The models run inside your own environment, so proprietary data and confidential records never leave your infrastructure.

Fully editable for perfection

Every exhibit, table, and slide stays editable. Refine any element with a prompt or edit it directly until it is exactly right.

Works with any AI model of your firm's choice

Pick the model per task and balance accuracy against cost — ChatGPT, Claude, Gemini, Grok, DeepSeek, Qwen, and more.

Built for ambitious professionals

Explore AI solutions tailored to the work you do
Investment banking team reviewing a mandate

Investment Banking

Win the mandate with numbers you can defend

Management consultants working with a client

Management Consulting

Build consulting-grade deliverables in minutes

Private equity investors reviewing a deal

Private Equity

Screen, diligence, and underwrite more deals

Blogs

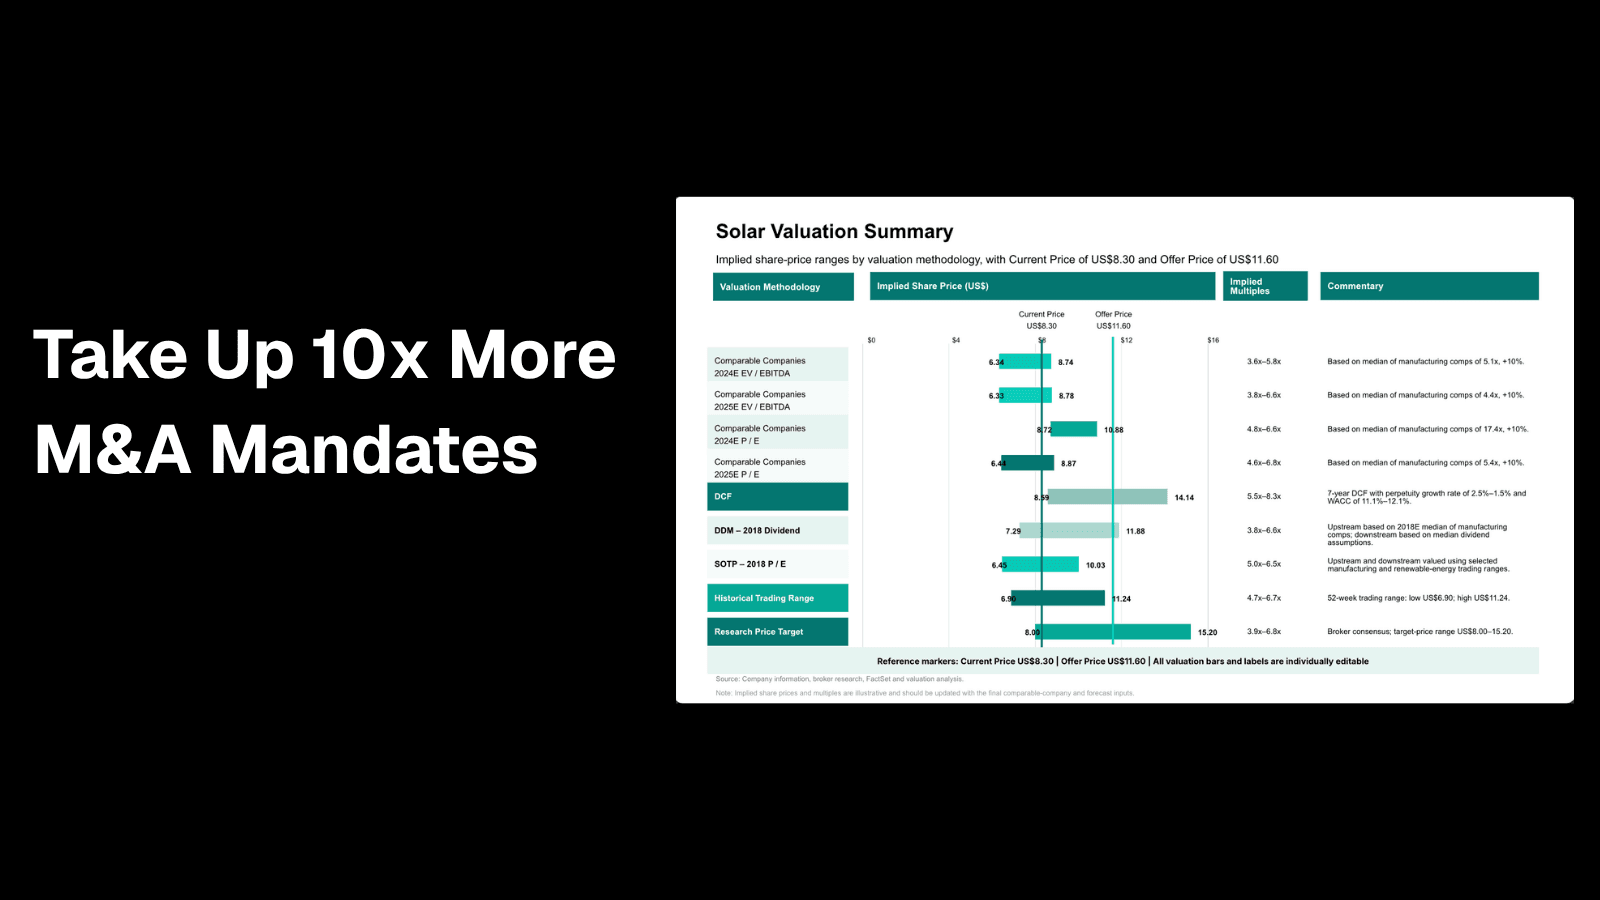
Take Up 10x More M&A Mandates
Finance·3 min read

Take Up 10x More M&A Mandates

The data is already sitting in the data room. What takes time is turning it into the deliverables needed to move a deal forward. AI can automate the entire M&A documentation lifecycle in 2 days instead of weeks, with every number auditable.

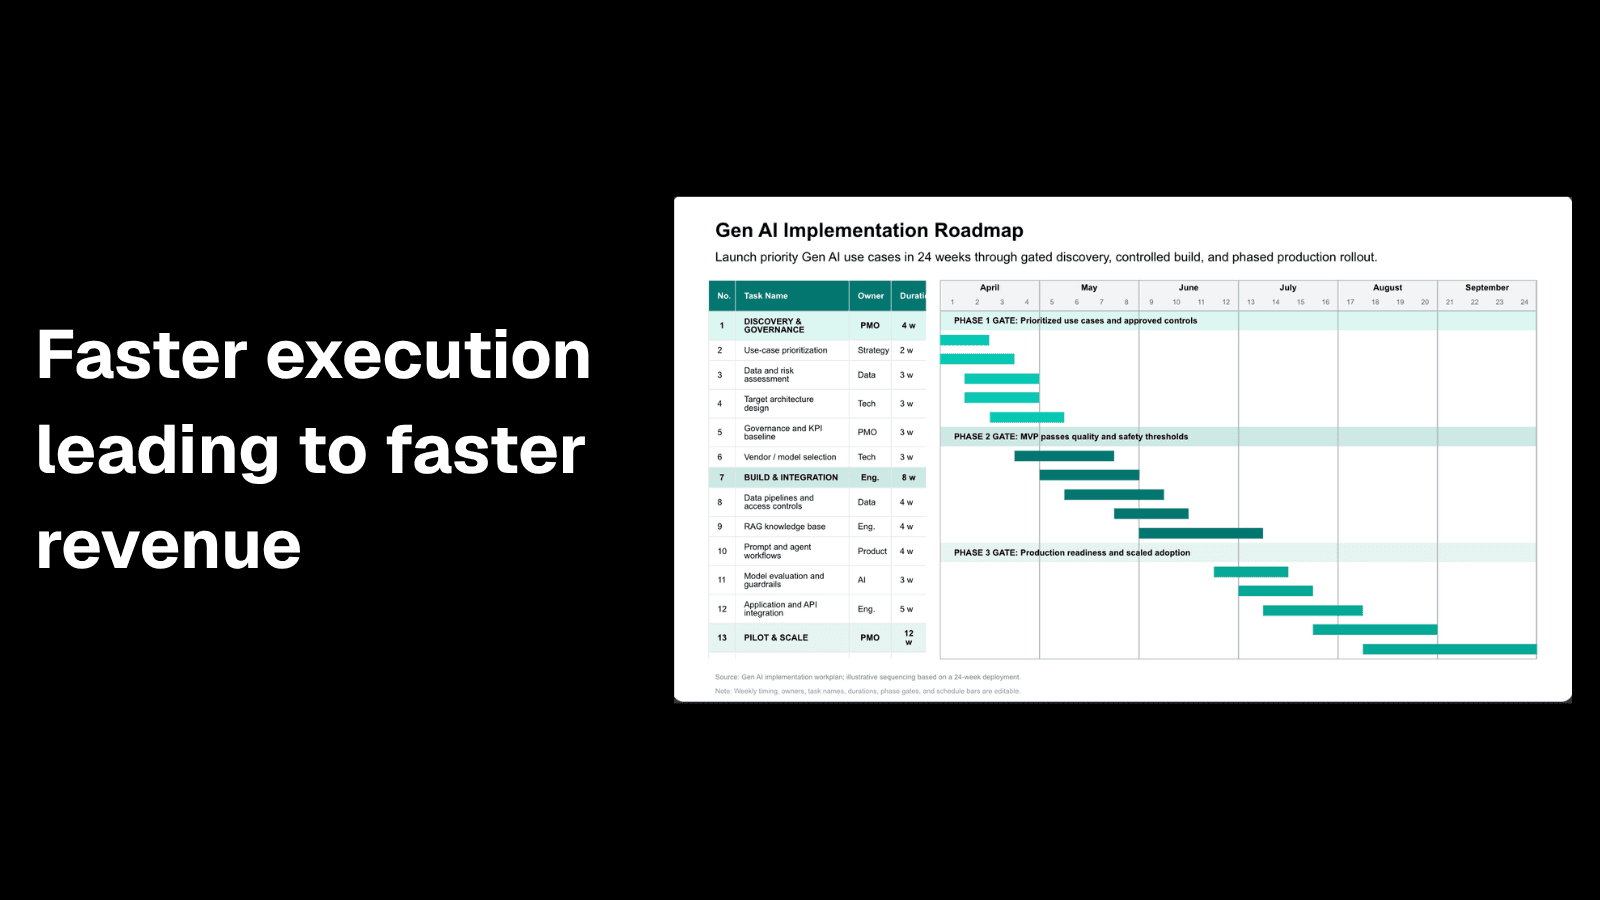
Faster execution leading to Faster revenue
Consulting·3 min read

Faster execution leading to Faster revenue

You pay consultants hundreds of thousands of dollars to tell you what you should do and then your team has to figure out how to actually do it. A strategy should tell you what to prioritize, the dependecies, when it needs to be done, who owns it and what could go wrong.

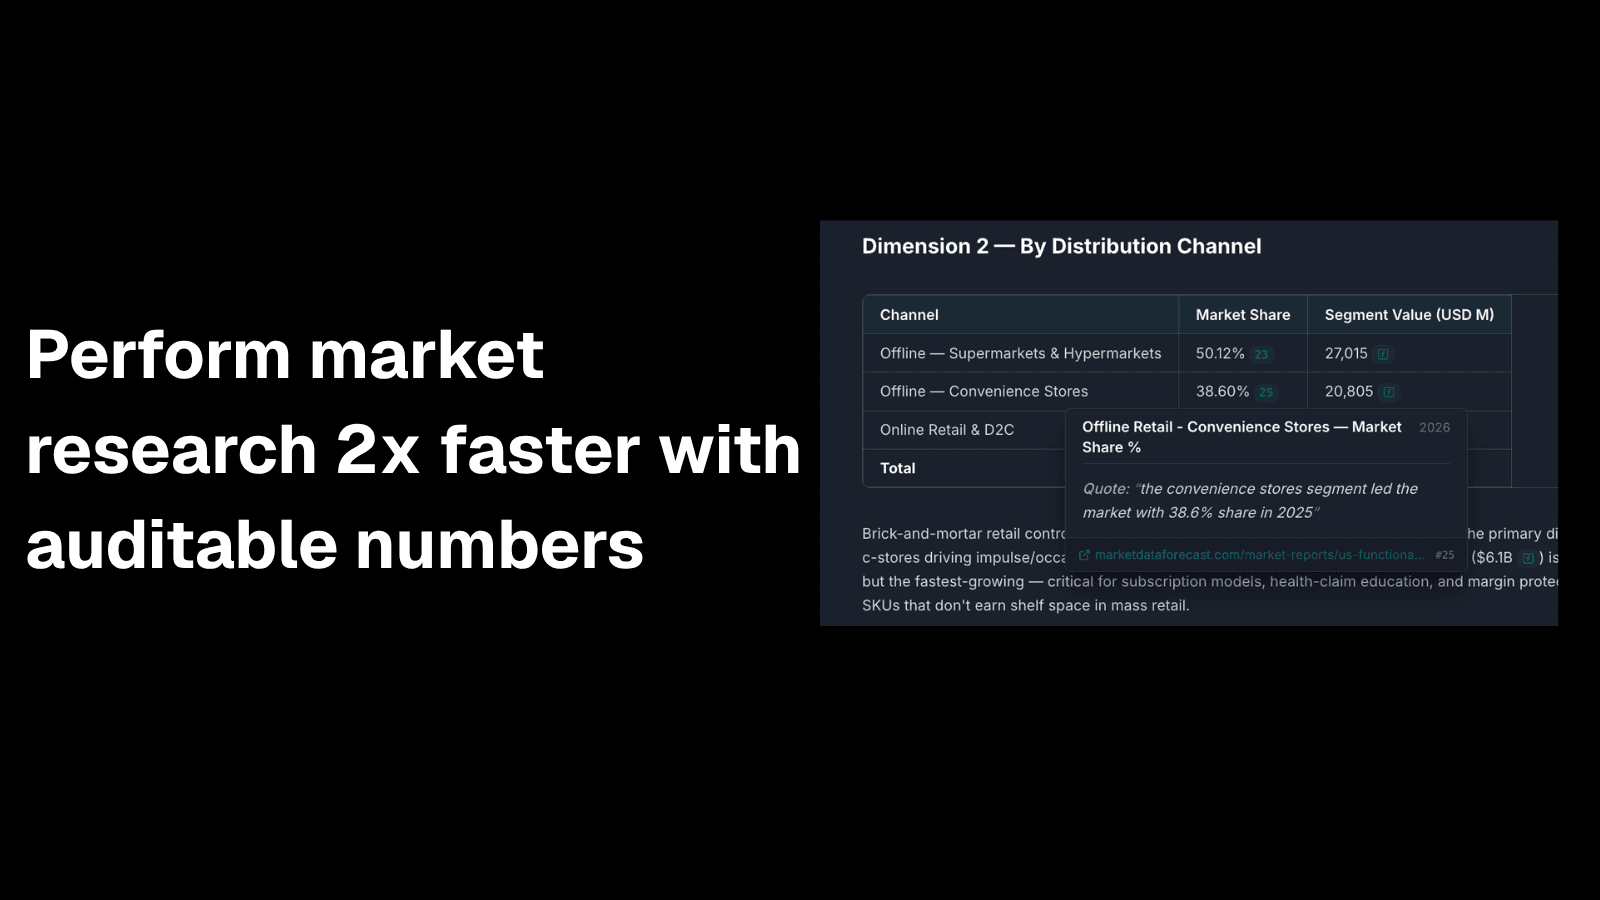
Perform Market Research 2x Faster With Auditable Numbers
Consulting·4 min read

Perform Market Research 2x Faster With Auditable Numbers

AI can produce a market size in minutes. The harder question is whether you can defend it. Here is how we build research from volume and value drivers, MECE segmentation, and evidence you can trace back to the exact quote.

View all posts

Testimonials

We spend a significant amount of time creating proposals for a client opportunity tailored to their specific requirements. WinningStrategy.ai helps us get the research and first draft of proposal done much faster, without compromising on whether the numbers can be defended.
Partner, Management Consulting
The biggest value that WinningStrategy.ai provides us is the way it builds the story and structures the analysis around research, using consulting frameworks. It has helped in increasing the number of engagements that we undertake.
Managing Director, Investment Banking
Our senior team should be spending time on the client and the investment thesis, not chasing analysts for source validation. Having the research structured and traceable from the start changes how quickly we can move.
Partner, Strategy Consulting
We can now turn around research and client-ready presentations with far less manual effort. That gives the team more capacity to pursue opportunities without immediately needing to add more people.
Director, Advisory
AI-generated work is only useful if you can trust it. What stood out with WinningStrategy.ai was that the output was not just fast, the underlying numbers were traceable, which is critical when the work is going in front of clients.
Managing Director, Financial Advisory
We spend a significant amount of time creating proposals for a client opportunity tailored to their specific requirements. WinningStrategy.ai helps us get the research and first draft of proposal done much faster, without compromising on whether the numbers can be defended.
Partner, Management Consulting
The biggest value that WinningStrategy.ai provides us is the way it builds the story and structures the analysis around research, using consulting frameworks. It has helped in increasing the number of engagements that we undertake.
Managing Director, Investment Banking
Our senior team should be spending time on the client and the investment thesis, not chasing analysts for source validation. Having the research structured and traceable from the start changes how quickly we can move.
Partner, Strategy Consulting
We can now turn around research and client-ready presentations with far less manual effort. That gives the team more capacity to pursue opportunities without immediately needing to add more people.
Director, Advisory
AI-generated work is only useful if you can trust it. What stood out with WinningStrategy.ai was that the output was not just fast, the underlying numbers were traceable, which is critical when the work is going in front of clients.
Managing Director, Financial Advisory

Winning Strategy FAQ

Find answers to common questions about Winning Strategy — consulting-grade presentations and analysis, from a single prompt, with auditable numbers

Winning Strategy turns a single prompt into consulting-grade presentations and analysis — grounded in in-depth research where every number is auditable to its source. It's built for experts — consultants, strategic sales heads, investment bankers, and executives — who need board-room-ready deliverables they can defend, not generic AI output.
Generic AI tools produce generic, surface-level output you can't verify. Winning Strategy does the opposite: it performs in-depth research and analysis, structures it using proven consulting frameworks, and makes every number auditable — traced to a verifiable source with line-by-line rationale. The result is analyst-grade work you can stand behind in front of clients and boards.
Winning Strategy offers three specialized agents: the AI Presentation Agent for board-ready decks with cited, verifiable research; the AI Spreadsheet Agent for financial models with multi-sheet linkages and fully traceable formulas; and the AI Dashboarding Agent for market and deal analysis proven with statistical tests and machine learning — all without coding.
Getting started is simple! Sign up for an account, choose a plan that fits your needs, and you'll have immediate access to all three AI agents — the AI Presentation Agent, AI Spreadsheet Agent, and AI Dashboarding Agent. The platform guides you through your first deliverable, and our support team is always ready to help.
Yes, Winning Strategy is designed for businesses of all sizes, from individual professionals to large firms. We offer customizable solutions, enterprise-grade security, role-based access control, and the option to deploy locally on your own servers — so teams handling sensitive deal, client, or board data stay fully in control.
Winning Strategy serves experts who live and die by their deliverables — consultants, strategic sales heads, investment bankers, and executives across corporate strategy, private equity, and finance. Any team that needs board-room-ready presentations and analysis with auditable numbers can rely on it.
View All FAQs
Winning Strategy - Consulting-grade presentations and analysis with auditable numbers
WinningStrategy.ai

Winning Strategy turns a single prompt into consulting-grade presentations and analysis — grounded in in-depth research where every number is auditable to its source.

Trusted by consultants, strategic sales heads, investment bankers, and executives.

Our AI Agents

  • AI Dashboarding Agent
  • AI Spreadsheet Agent
  • AI Presentation Agent

Company

  • About Winning Strategy
  • Pricing Plans
  • FAQ
  • Contact Us
  • Book a Demo

Follow Us

Find us on CodeHypeFazier badgeFeatured on neeed.directoryFeatured on LaunchIgniterLaunched on StartupBase
Privacy PolicyTerms of ServiceRefund PolicyShipping Policy

© 2026 WinningStrategy.ai. All rights reserved.

Winning Strategy Consulting Private Limited | Consulting-grade Presentations & Analysis with Auditable Numbers